The key to significantly reducing your fleet insurance premiums isn’t just safer driving; it’s proving your commitment to risk management with irrefutable data presented as a financial case to your underwriter.
- Positive reinforcement and gamification are statistically more effective at reducing collisions than punitive measures.
- Controlling operational habits like vehicle idling and unauthorized use provides tangible proof of a disciplined, lower-risk fleet.
Recommendation: Begin by implementing a driver scorecard program focused on 2-3 key behaviors (e.g., idling time, harsh braking) and present the 90-day improvement data to your insurance broker before your next renewal negotiation.
As a fleet owner, you’ve felt the pressure. Insurance premiums climb relentlessly, often driven by a handful of incidents that don’t reflect your entire operation. You’re told to « train your drivers » and « maintain your vehicles, » but this generic advice rarely moves the needle on your renewal quote. The frustration is understandable; it feels like you’re being penalized for risks you can’t fully control. The conventional approach to fleet safety focuses on reacting to accidents, a strategy that leaves you perpetually on the defensive with your insurer.
The truth is, most fleets are sitting on a goldmine of untapped financial leverage: their telematics data. The mistake is viewing this data solely as an operational tool for tracking locations or hours. Its real power lies in its ability to tell a proactive story of risk mitigation. Instead of just monitoring drivers, what if you could quantify and prove a culture of safety? What if you could demonstrate, with hard numbers, that your fleet is a better risk today than it was six months ago? This is the shift from passive monitoring to active, data-driven discipline.
This guide moves beyond the platitudes. We will not tell you to simply « install GPS. » Instead, we will provide a broker’s inside perspective on how to transform specific, often-overlooked data points into a compelling risk narrative. We will explore how to use gamification to foster safe habits, how managing idling signals financial discipline, and how to identify the precise data patterns that precede costly collisions. By the end, you will have a clear framework for turning your telematics system into your most powerful tool for negotiating—and securing—lower insurance premiums.
This article provides a detailed roadmap for transforming your operational data into a powerful negotiating tool. Below is a summary of the key strategies we will cover to help you build an undeniable case for lower insurance premiums.
Summary: A data-driven strategy to reduce fleet insurance costs
- Why Gamification Works Better Than Punishment for Driver Safety?
- How to Cut Fuel Costs by 10% Simply by Managing Idling?
- Company Car vs. Mileage Reimbursement: Which Reduces Liability?
- The Geofencing Mistake That Allows Employees to Moonligth with Your Trucks
- When to Sell Fleet Vehicles: The Mileage Sweet Spot for Resale Value?
- The Data Pattern That Precedes 80% of Highway Collisions
- Gas vs. Electric Fleets: Which Option Offers Better TCO Over 5 Years?
- How to Reduce Fuel Consumption by 15% Without Buying New Trucks?
Why Gamification Works Better Than Punishment for Driver Safety?
For decades, fleet safety has been rooted in a culture of punishment: penalties for speeding, warnings for harsh braking, and disciplinary action after an incident. While this approach can curb the most egregious behaviors, it fosters a climate of anxiety and resentment, not genuine improvement. The modern, data-driven approach flips this model on its head by using gamification. Instead of punishing the bad, you reward the good, creating a positive feedback loop that encourages lasting behavioral change. This isn’t about fun and games; it’s about leveraging human psychology to achieve measurable financial results.
The core principle is simple: drivers who are positively engaged with their performance are safer drivers. By creating leaderboards, awarding badges for achievements (like a month without a harsh braking event), or offering small bonuses for top-performing teams, you transform safety from a mandate into a competition. This fosters a sense of ownership and pride. When presented to an underwriter, a well-documented gamification program is not just a driver perk; it’s evidence of a proactive, positive safety culture. It demonstrates that you are actively reducing risk, a far more compelling argument than simply having a list of rules. Industry data confirms this, showing a 49% reduction in collision risk for fleets that implement gamified coaching.
One powerful example is SGN, a gas distribution company, which saw dramatic improvements by introducing depot-based performance comparisons. This team-based competition led to a 68% reduction in idling and a 16% drop in mileage. The key takeaway for your insurer is that your fleet’s safety program is built on continuous improvement and positive reinforcement, which is statistically proven to be more effective at preventing claims than a system based solely on punishment.
Ultimately, a gamified system provides a steady stream of positive data points—proof of engagement and improvement—that you can present at every insurance renewal, building a long-term case for being a preferred-risk client.
How to Cut Fuel Costs by 10% Simply by Managing Idling?
Excessive idling is one of the most visible and costly habits in any fleet operation. It’s often dismissed as a minor operational inefficiency, but to an insurance underwriter, it’s a bright red flag. Pervasive idling suggests a lack of driver discipline and operational control—two factors that correlate directly with higher claim frequency. When a driver is careless with your fuel, an underwriter will assume they are also careless with your vehicle. Therefore, tackling idling is not just a fuel-saving initiative; it’s a critical step in demonstrating the kind of data-driven discipline that earns you lower premiums.
The financial impact of idling is staggering, wasting fuel, causing unnecessary engine wear, and increasing emissions. The goal is to use your telematics data to move from simply knowing idling occurs to systematically eliminating it. By identifying « idling hotspots »—specific locations like depots, job sites, or lunch spots where vehicles consistently run for extended periods—you can pinpoint the root cause. Is it inefficient scheduling? Lack of driver awareness? Unclear company policy? Once identified, you can implement targeted solutions, such as automated engine shutdowns or driver-specific coaching.
Presenting a report to your insurer that shows a 50% reduction in average idle time over six months is powerful. It’s quantifiable proof that you are actively managing your fleet to a higher standard. The case of Dohrn Transfer Company, which saved over $500,000 annually by reducing idle time by 50%, shows the scale of the opportunity. Your narrative to the underwriter is clear: « We have identified a risk behavior, implemented a data-backed solution, and achieved a measurable result. This discipline extends to everything we do. »
Action Plan: Idling Hotspot Analysis for Insurers
- Use telematics to identify specific locations and times where excessive idling occurs systematically across your fleet.
- Implement geofencing around these identified hotspot locations to capture precise idle duration data for each vehicle entry and exit.
- Analyze root operational causes by correlating idle times with job schedules, client wait times, or inefficient route planning.
- Set automated idle time limits (e.g., 5 minutes) with alerts or auto-shutdown features to enforce policy and prevent unnecessary engine runtime.
- Generate quarterly idling reduction reports to present to your insurer as hard evidence of improved fleet discipline and a reduced overall risk profile.
This proactive management of a single metric—idling—serves as a powerful proxy for your entire operational philosophy, making your fleet a more attractive and less risky proposition for any insurer.
Company Car vs. Mileage Reimbursement: Which Reduces Liability?
The choice between providing a company-owned vehicle and reimbursing employees for using their personal car (the « grey fleet ») seems like a simple financial decision. However, from a liability and insurance perspective, the difference is night and day. A company-owned vehicle is a known, managed asset. You control its maintenance, you ensure it is properly insured for commercial use, and you can mandate the installation of telematics and safety equipment. This level of liability control is precisely what insurance underwriters want to see.
A grey fleet, on the other hand, is a universe of unknowns. You have little to no control over the vehicle’s condition, maintenance schedule, or tire quality. More critically, you are exposed to significant insurance gaps. Many personal auto policies explicitly exclude coverage for business use. Research shows that one-in-six grey fleet drivers fail to inform their insurer they are using their vehicle for work, potentially voiding their coverage in the event of an accident. If an employee is involved in a serious collision while on company business, your company will almost certainly be named in the lawsuit, and you may find yourself with inadequate or non-existent coverage.
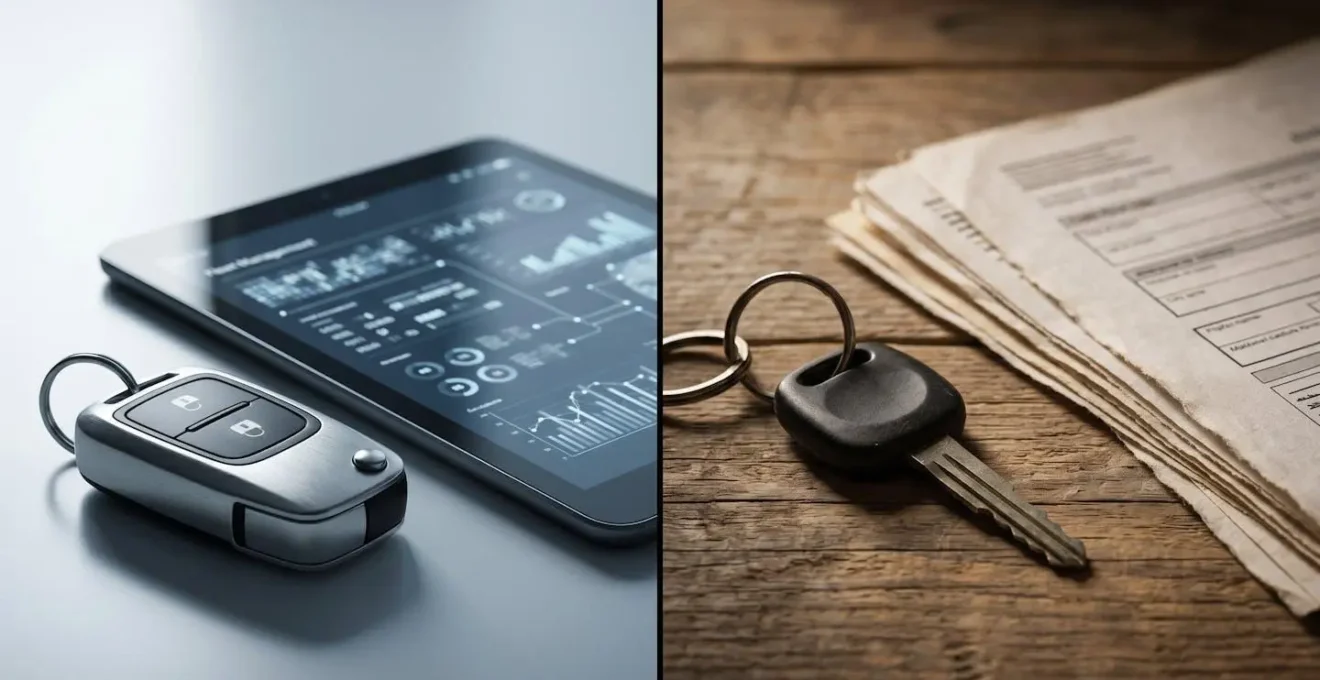
As the image above illustrates, the contrast is stark. The company car represents a controlled, transparent risk, while the personal vehicle introduces a host of unmanaged variables. From an underwriter’s viewpoint, a fleet of company-owned vehicles equipped with telematics is a vastly superior risk to a grey fleet. While mileage reimbursement may seem cheaper on a spreadsheet, the potential for a single, uncovered catastrophic claim can dwarf any perceived savings. The higher cost of a company car program is, in reality, the price you pay for control—a price that is often offset by significantly lower liability insurance premiums.
When you present your fleet to an insurer, being able to state that 100% of your vehicles are company-owned and monitored is a powerful statement that immediately reduces your perceived risk profile.
The Geofencing Mistake That Allows Employees to Moonligth with Your Trucks
Most fleet managers use geofencing for basic functions, like setting a virtual perimeter around a depot to log start and end times. This is a missed opportunity. The most common and costly mistake is configuring geofences without considering time-based rules. A simple « in or out » geofence is blind to a critical risk: an employee using your vehicle for unauthorized side-jobs (moonlighting) or personal use after hours, even if the vehicle is returned to the depot by morning. This unauthorized use dramatically increases your liability, as your vehicle is on the road when it shouldn’t be, often driven by a fatigued employee, outside of your operational control.
Advanced geofencing is your primary defense against this hidden risk. Instead of a simple perimeter, you should configure time-based rules. For example, a geofence around your main yard should trigger an immediate alert if a vehicle *leaves* the area between 7 PM and 5 AM. This isn’t about distrusting employees; it’s about enforcing policy and controlling your assets. Another powerful technique is route corridor fencing, which creates a narrow virtual tunnel along a planned route and triggers an alert if the driver deviates significantly, preventing unauthorized detours to run personal errands or perform side work.
When properly configured, geofencing is incredibly effective. Fleets using these advanced techniques report up to a 95% elimination of unauthorized vehicle use. This is the kind of hard data that resonates with an underwriter. It provides undeniable proof that your vehicles are only being used for their intended business purpose, during approved hours, and along planned routes. You are actively neutralizing a major source of potential claims before they happen. This is the definition of proactive risk management and a cornerstone of building the case for a lower premium.
By presenting your insurer with a geofencing policy and violation reports, you demonstrate a level of control over your assets that few other fleets can match, making you a much lower-risk client.
When to Sell Fleet Vehicles: The Mileage Sweet Spot for Resale Value?
The lifecycle of your fleet vehicles is a critical component of your Total Cost of Ownership (TCO), and it has a direct, though often overlooked, impact on your insurance risk. Holding onto vehicles for too long introduces risks that underwriters notice. Older vehicles have a higher probability of mechanical failure—from brake issues to tire blowouts—that can lead to accidents. They also tend to lack the latest safety features like automatic emergency braking or advanced stability control, which are becoming standard on newer models. A fleet composed of aging, high-mileage vehicles signals to an insurer that cost-cutting may be prioritized over safety and reliability.
The key is to identify the « mileage sweet spot » for selling your vehicles. This isn’t a single number, but a calculated financial window where the vehicle’s resale value decline begins to accelerate, and its maintenance and repair costs begin to rise sharply. This point often coincides with the expiration of the manufacturer’s powertrain warranty. Operating a vehicle outside of its warranty period means you bear 100% of the cost for major component failures, creating financial volatility and increasing the risk of a maintenance-related accident.
A structured vehicle replacement plan, or « cycling » strategy, is a powerful tool in insurance negotiations. For light-duty trucks, this sweet spot might be between 75,000 and 100,000 miles. For heavy-duty trucks, it could be closer to 400,000 miles. The exact number depends on the vehicle type, usage, and market conditions. By establishing a policy—for example, « We replace all light-duty vehicles before they reach 100,000 miles or 5 years of service »—you create a predictable, modern, and reliable fleet. This allows you to present your vehicle roster to an underwriter not as a collection of aging assets, but as a professionally managed, low-risk portfolio where the likelihood of age-related failures is systematically minimized.
A disciplined cycling strategy proves that your approach to fleet management is proactive and strategic, directly contributing to a lower-risk profile and justifying a lower premium.
The Data Pattern That Precedes 80% of Highway Collisions
Experienced fleet managers know that major accidents rarely happen out of the blue. They are almost always preceded by a pattern of smaller, seemingly minor risky behaviors. Telematics data now gives us the ability to see this pattern with startling clarity. The data pattern that precedes the majority of highway collisions is not a single event, but a cascade of interconnected behaviors: a driver who consistently speeds is also more likely to brake harshly, follow too closely, and take corners too aggressively. These are not isolated incidents; they are symptoms of an aggressive or inattentive driving style that dramatically increases the probability of a major collision.
Your telematics system captures each of these events. The key is to stop looking at them in isolation. A single speeding alert is noise; a driver who generates alerts for speeding, harsh braking, and rapid acceleration all in the same trip is a high-risk individual. This is the pattern. By setting up a driver scorecard that weights these cascading behaviors, you can identify your top 10% of high-risk drivers *before* they have an accident. This allows for targeted intervention—coaching, training, or disciplinary action—to break the pattern.
The impact of focusing on this pattern is profound. As the abstract visualization suggests, these small events build on each other until they reach a critical point. By intervening early, you disrupt the cascade. In fact, one leading telematics provider reported that focusing on these predictive indicators delivered an 80% reduction in risky driver behavior and a 40% reduction in at-fault collisions. When you sit down with your underwriter, you can present this strategy as a form of predictive analytics. You are not just reacting to incidents; you are statistically reducing the likelihood of them ever happening. This is the most powerful argument you can make for a premium reduction.
By demonstrating that you can see and neutralize risk before it materializes, you position your fleet as a top-tier, data-savvy operation worthy of the best possible insurance rates.
Gas vs. Electric Fleets: Which Option Offers Better TCO Over 5 Years?
The decision to transition a fleet from internal combustion engine (ICE) vehicles to electric vehicles (EVs) is a major strategic choice with significant financial implications. While the higher upfront purchase price of EVs is a deterrent for many, a sophisticated analysis of Total Cost of Ownership (TCO) over a typical 5-year cycle often reveals a different story. For an insurance broker and an underwriter, a fleet’s decision to electrify can be a strong positive signal about its long-term approach to risk and financial management.
The TCO calculation for an EV fleet extends far beyond fuel savings. EVs have fewer moving parts, leading to substantially lower maintenance costs—no oil changes, spark plugs, or exhaust systems to repair. They also benefit from regenerative braking, which reduces wear on brake pads and rotors. While electricity is not free, its cost is generally lower and more stable than volatile gasoline or diesel prices. Furthermore, various government incentives, tax credits, and rebates can significantly reduce the effective acquisition cost of EVs. Comprehensive fleet management strategies, even on ICE vehicles, can achieve a 15-30% reduction in fleet fuel costs, but EVs eliminate this cost category almost entirely for local and regional routes.
From a risk perspective, EVs also present a compelling case. Many are equipped with advanced driver-assistance systems (ADAS) as standard features. The smooth, quiet operation can lead to a less fatiguing driving experience. While there are new risks to manage (e.g., battery health, charging infrastructure), an insurer will view a well-planned EV transition as a sign of a forward-thinking, technologically adept organization. It shows a commitment to long-term financial planning and operational efficiency, qualities that define a low-risk client.
While not every fleet is ready for a full transition today, presenting a phased EV adoption plan to your insurer can be a powerful part of your long-term strategy to control costs and reduce premiums.
Key Takeaways
- Proactive risk management, proven with data, is more persuasive to insurers than a simple record of few accidents.
- Driver behavior metrics (idling, speeding, braking) are direct indicators of operational discipline and future claims probability.
- Controlling your fleet’s assets through company-owned vehicles, geofencing, and structured replacement cycles significantly reduces hidden liabilities.
How to Reduce Fuel Consumption by 15% Without Buying New Trucks?
For most fleets, fuel is the largest or second-largest operating expense. While purchasing new, more fuel-efficient vehicles is one solution, it’s not always financially feasible. The most immediate and cost-effective way to reduce fuel consumption by up to 15% or more lies in changing driver behavior. The critical insight for you as a fleet owner—and for your insurer—is that the very same behaviors that waste fuel are the ones that cause accidents. An aggressive driver who speeds, brakes late, and accelerates hard is not just burning excess fuel; they are actively creating risk.
According to analysis from the U.S. Department of Energy, aggressive driving habits can lower fuel economy by 15% to 30% at highway speeds and by 10% to 40% in stop-and-go traffic. This provides a direct financial incentive to promote a smoother, more defensive driving style. By using telematics to monitor metrics like « greenband » driving (staying within the optimal RPM range), high torque events, and time-in-top-gear, you can create a clear picture of which drivers are efficient and which are not. This data forms the basis for a powerful, cost-focused coaching program.
The success of this approach is well-documented. For instance, GP Transco implemented a « Fuel Leaders » gamification program based on these metrics, saving $350,000 annually. The beauty of this strategy is that it creates a win-win-win scenario. The company saves money on fuel, the drivers (if incentivized) can earn bonuses, and the insurer sees a direct reduction in the risky behaviors that lead to claims. As the U.S. Department of Energy points out:
The same behaviors—smooth driving, anticipating traffic to avoid braking, optimal speed—reduce both fuel use and accident probability.
– U.S. Department of Energy Alternative Fuels Data Center, Efficient Driving to Conserve Fuel
When you show an underwriter your fuel efficiency reports, you are simultaneously showing them your safety performance reports. You are proving that your fleet is not only cheaper to run but fundamentally safer to insure.
By framing your fuel-saving initiatives as a core part of your safety program, you complete the risk narrative, demonstrating that every aspect of your operation is managed with an eye toward discipline, efficiency, and safety. This is the final piece of the puzzle in building an unassailable case for the lowest possible insurance premiums.