From an actuarial standpoint, advanced safety systems do not automatically guarantee lower insurance premiums because they introduce a new, complex risk profile that can offset their benefits.
- System performance is unreliable outside a narrow operational envelope (e.g., heavy rain, low light), limiting their real-world effectiveness.
- High-cost repairs and mandatory calibrations after minor incidents often increase the total cost of claims, negating savings from accident reduction.
Recommendation: Evaluate the technology not as a guaranteed discount, but as a complex trade-off between potential accident avoidance and new financial liabilities related to maintenance, repair, and operational failures.
For the modern car buyer, the pitch is compelling: invest in an advanced safety package and reap the rewards of a safer vehicle and, presumably, lower insurance premiums. The logic seems undeniable. Features like Automatic Emergency Braking (AEB) and Lane-Keeping Assist are designed to prevent the very accidents that drive up insurance costs. Many buyers assume a direct correlation—more tech equals an immediate discount. This is the surface-level understanding.
However, from an insurance actuary’s perspective, the equation is far more complex. Our business is not just about rewarding safety; it’s about pricing risk with statistical precision. While these systems show promise, they also introduce new variables and liabilities that are not yet fully understood or quantified. The initial promise of risk reduction is often complicated by operational failures, exorbitant repair costs, and even negative changes in driver behavior. These factors create a new, multifaceted risk profile that can neutralize, or in some cases even increase, the net financial exposure for an insurer.
The central question is no longer simply, « Is the car safer? » It has evolved into, « What is the total cost-loss ratio of this technology over the vehicle’s lifespan? » This analysis moves beyond the showroom floor to examine the real-world performance and financial implications of these systems. We will deconstruct the actuarial calculus behind ADAS, exploring why the initial safety promise doesn’t always translate into a straightforward premium reduction. This guide will provide a framework for evaluating the true return on investment of that expensive safety tech package.
This article dissects the key data points and risk factors that influence an insurer’s assessment of advanced safety systems. The following sections provide a detailed breakdown of the technology’s limitations, liabilities, and the underlying statistical realities that shape your insurance premium.
Summary: An Actuarial View on ADAS and Insurance Costs
- Why Automatic Braking Fails at Night or in Heavy Rain?
- Airbags vs. Collision Avoidance: Which Saves More Lives statistically?
- The Sensor Glitch That Can Disable Your Car on the Highway
- The « Automation Complacency » That Makes You a Worse Driver
- When to Sell: Do Old Safety Systems Become a Liability?
- The Data Pattern That Precedes 80% of Highway Collisions
- Dynamic vs. Static Calibration: Which Method is Required for Your Camera?
- How to Prevent « Phantom Braking » Events on the Highway?
Why Automatic Braking Fails at Night or in Heavy Rain?
The primary assumption about Automatic Emergency Braking (AEB) is that it functions as a vigilant co-pilot, always ready to intervene. However, an actuarial analysis must focus on the system’s « operational envelope »—the specific conditions under which it performs reliably. Data shows this envelope is surprisingly narrow. The sensor fusion technology, typically a combination of cameras and radar, has inherent weaknesses. As noted in industry analyses, cameras struggle in low light, radar has difficulty classifying stationary objects, and even advanced LiDAR can be compromised by adverse weather.
This isn’t theoretical. Controlled testing reveals a significant degradation in performance when conditions are suboptimal. For a prospective owner, this means the system you’re paying a premium for may not be effective during a nighttime drive or a sudden downpour. To an insurer, this variability is a critical risk factor that tempers the system’s overall benefit. The following illustration highlights the environmental challenges these sensors face.
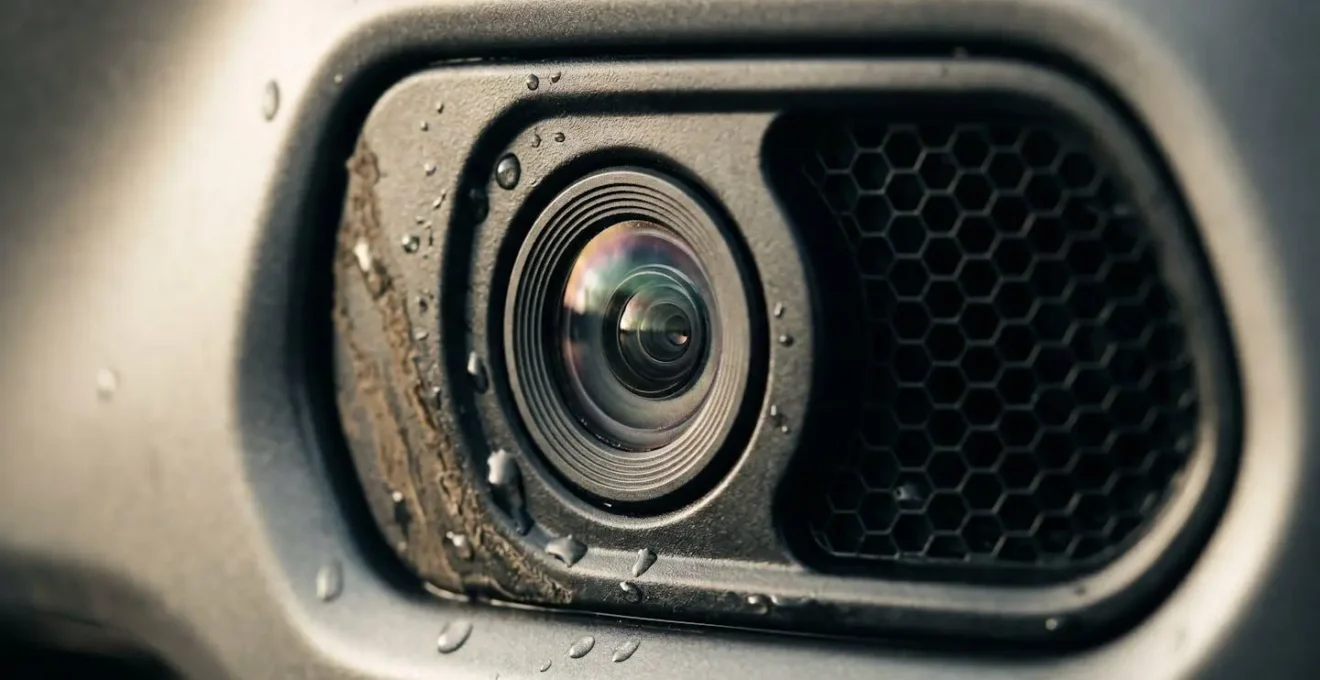
The practical implication is a measurable increase in collision risk under common driving conditions. For instance, recent closed-course testing by the AAA revealed a stark reality: when encountering a stopped vehicle at 35 mph in simulated heavy rain, vehicles equipped with AEB still had a 33% collision rate. This statistical reality directly impacts the cost-loss ratio, as the system fails to prevent a significant portion of claims in scenarios where it is most needed.
Airbags vs. Collision Avoidance: Which Saves More Lives statistically?
To evaluate the financial impact of new technology, actuaries often benchmark it against established systems with known risk profiles. Airbags represent a mature « passive » safety technology. Their function is not to prevent a crash, but to mitigate its severity. The data is extensive and clear: the NHTSA confirms that frontal airbags reduce driver fatalities by 29% in otherwise fatal crashes. This is a known, predictable reduction in the most severe (and costly) claims, making it a cornerstone of vehicle risk rating.
In contrast, « active » systems like AEB aim to prevent the crash from happening at all. On paper, this is superior. Studies of police-reported incidents found that AEB reduced rear-end crashes by 39%. However, this statistic comes with crucial caveats for an actuary. Firstly, it applies specifically to rear-end collisions, not all accident types. Secondly, the effectiveness is highly dependent on the operational envelope discussed previously. Unlike an airbag, which deploys based on physical forces, an AEB system’s success is a probability, not a certainty.
The actuarial challenge lies in this variability. An airbag’s life-saving benefit is a stable, reliable data point. The benefit of AEB, while significant, is a fluctuating variable influenced by weather, light, speed, and system calibration. This makes its impact on the overall cost-loss ratio harder to predict. While it demonstrably prevents a large number of low-speed fender-benders, its reliability in preventing high-cost, high-severity accidents is less certain. Therefore, from a pure risk-pricing perspective, the proven severity reduction of an airbag often carries more weight than the variable frequency reduction of AEB.
The Sensor Glitch That Can Disable Your Car on the Highway
A core component of actuarial analysis is assessing not just the primary function of a system, but also its failure modes and associated costs. Advanced safety systems introduce a new category of risk: high-cost electronic failures that can be triggered by low-cost physical problems. The complexity of these integrated systems creates a « cascade failure » liability, where a minor issue can disable multiple critical functions and lead to an expensive and often incorrect diagnosis.
This creates a significant financial risk that directly impacts the total cost of ownership and, by extension, the insurance risk profile. A simple layer of mud or ice on a sensor can not only disable the safety system but also trigger a series of warning lights that can be alarming to the driver and costly to diagnose. This moves the risk from a potential collision to a definite maintenance and repair liability.
Case Study: The Honda « Dirty Sensor Cascade »
An analysis of widespread failures in Honda’s Forward Collision Warning (FCW) system illustrates this risk perfectly. It was discovered that a single, inexpensive $40 wheel speed sensor malfunction could trigger a cascade of warnings, illuminating the FCW, ABS, and Vehicle Stability Assist (VSA) lights simultaneously. Mechanics, unfamiliar with the root cause, frequently misdiagnosed this as a failure of the primary radar unit, quoting repairs of up to $1,500. The most common trigger for these system failures was found to be even simpler: mud, ice, or road salt obscuring the radar sensor, which is often located behind the front grille emblem. The « fix » in these cases is simply cleaning the sensor, costing nothing.
This scenario highlights a transfer of liability. The risk of a low-speed collision is partially replaced by the near-certainty of high-cost diagnostics and repairs over the vehicle’s life. For an insurer, this means that while collision claim frequency may decrease, the frequency and cost of comprehensive or repair-related claims could rise, offsetting the benefit.
The « Automation Complacency » That Makes You a Worse Driver
The most unpredictable variable in any vehicle is the human behind the wheel. Advanced safety systems fundamentally alter the relationship between driver and machine, and not always for the better. A significant risk factor that actuaries are now modeling is « automation complacency »—a psychological phenomenon where drivers become overly reliant on ADAS, leading to decreased vigilance and slower reaction times when the system fails or reaches its operational limit. This human-factor risk can actively negate the safety benefits of the technology.
This isn’t just a theory; it’s a documented source of accidents. For example, in 2019, Japanese authorities reported 80 accidents over a 9-month period directly attributed to driver overconfidence in automatic braking systems. Drivers, believing the car would stop for them, failed to apply the brakes manually. This demonstrates that the technology, while reducing certain types of errors, can create new, predictable forms of human error. As one research team noted, understanding the driver’s mental model is critical:
It is imperative to understand how drivers develop their mental model of these systems and how their experiences with different implementations of the technologies affect their opinions, attitudes and experiences.
– The Zebra Research Team, Why Tech That Makes Your Car Safer Won’t Lower Your Insurance Rates
For an insurer, this means the risk isn’t eliminated; it’s transformed. The random risk of momentary driver inattention is replaced by the more systemic risk of a disengaged driver who may be unprepared to take control during a system failure. This behavioral adaptation is a crucial variable. If a feature makes a driver 10% less likely to cause an accident but also 30% slower to react when that feature fails, the net result can be a negative outcome in high-stakes scenarios.
When to Sell: Do Old Safety Systems Become a Liability?
The financial analysis of a vehicle’s safety systems must extend beyond the purchase price and potential insurance discounts. A critical factor, especially for long-term owners, is the technology’s end-of-life cost and liability. Unlike purely mechanical components, ADAS sensors and control units have a finite lifespan and are exceptionally expensive to repair or replace. Furthermore, they require precise calibration that becomes a significant, recurring maintenance liability, particularly after common events like a windshield replacement or minor front-end damage.
As a vehicle ages, the probability of sensor failure or decalibration increases. At a certain point, the cost of maintaining the integrity of these safety systems can outweigh their benefit, turning a perceived asset into a tangible financial liability. A 10-year-old car with a malfunctioning AEB system is arguably more dangerous than one without it, as it may have fostered years of driver complacency. This aging tech liability is a growing concern for the secondary market and for insurers covering older vehicles.
The cost of keeping these systems functional is not trivial. Calibration is mandatory after many common repairs, and the costs are substantial, as shown in a recent analysis of service costs. These expenses are now a standard part of collision repair claims, driving up the average claim cost.
| Calibration Type | Complexity Level | Typical Cost Range (2025) | Common Trigger Events |
|---|---|---|---|
| Basic Static | Low | $150 – $300 | Single camera alignment |
| Standard Multi-System | Medium | $300 – $600 | Windshield replacement |
| Complex Dynamic | High | $600 – $1,000+ | Front-end collision repair |
| Luxury/Multiple Systems | Very High | $1,000 – $1,500+ | Suspension work + sensor replacement |
For a car buyer, this data presents a critical decision point. The long-term cost of ownership for a vehicle with ADAS must include a budget for potential recalibration and sensor replacement. For an older vehicle, a single complex calibration could exceed the value of the feature itself, making it a poor financial proposition and a reason to consider selling the vehicle before such costs are incurred.
The Data Pattern That Precedes 80% of Highway Collisions
While reactive systems like AEB have a mixed actuarial profile, the future of automotive risk management lies in predictive analytics. The true value for insurers is not just in technology that reacts to an imminent crash, but in systems that can identify high-risk driving patterns long before a critical event occurs. The data streams from modern vehicles—telematics, GPS, and internal sensors—create a rich tapestry of behavioral information. The most significant breakthroughs in risk reduction are coming from the analysis of this data to identify precursors to collisions.
Fleet safety analyses have shown that the vast majority of collisions are not sudden, random events. They are often the culmination of a period of risky behavior. This is where the next generation of systems is focused. As one analysis notes, the goal is to move from reaction to preemption: « This isn’t just about ADAS reacting to an event. It’s about onboard computers and telematics identifying driver fatigue, erratic lane keeping, or tailgating patterns before a critical situation. »
This data-driven approach allows for a more accurate and individualized risk profile. Insurers are increasingly looking at patterns like:
- Inconsistent following distances.
- Frequent, hard braking events outside of city traffic.
- Erratic steering or weaving within a lane, indicative of fatigue or distraction.
- Speeding patterns relative to traffic flow, not just the speed limit.
This is the data that truly matters. A driver who consistently maintains a safe following distance, as depicted below, presents a far lower risk profile than one who relies on AEB to save them from chronic tailgating. The future of insurance discounts will likely be tied less to the mere presence of ADAS and more to the verifiable data that shows a driver is using the road responsibly.
Dynamic vs. Static Calibration: Which Method is Required for Your Camera?
The conversation about ADAS liability inevitably leads to the topic of calibration. This is not an optional tune-up; it is a mandatory procedure required to ensure the system’s sensors are aimed with geometric precision. A failure to perform a correct calibration after a common service event, like a windshield replacement or even a wheel alignment, can render the entire safety suite unreliable or, worse, actively dangerous. The financial and safety stakes are immense, as a misaligned sensor can lead to system failure at a critical moment.
The precision required is staggering. As AAA research highlights, the consequences of even a minor error are magnified over distance: « Consider that a sensor on the car that is out of alignment by a fraction of an inch or even one degree will be aimed at an area significantly off axis 50 or more feet down the road. » This could mean the system fails to detect a pedestrian or brakes for a phantom object. This is why using the Original Equipment Manufacturer (OEM) specified calibration method is not just recommended; it’s a matter of liability.
Understanding the different types of calibration and when they are required is essential for any owner of a vehicle with ADAS. It is a direct and unavoidable cost of ownership that factors heavily into the actuarial risk of the vehicle. Making the wrong choice can lead to denied insurance claims and significant out-of-pocket expenses.
Action Plan: ADAS Calibration Method Selection
- Static Calibration: The vehicle remains stationary in a controlled workshop. Technicians use specialized targets placed at precise distances and angles to align the sensors. This method requires a large, level floor space and specific tools. It is often required for forward-facing cameras after windshield replacement.
- Dynamic Calibration: A technician drives the vehicle on well-marked roads, following specific patterns (e.g., maintaining a certain speed for a set distance) while the onboard software self-calibrates. This is often required for radar systems and may need to be done in sequence with a static calibration.
- Verify OEM Requirements: Always consult the manufacturer’s official repair procedures for the specific vehicle (identified by VIN). Some models mandate static-only, others dynamic-only, and many require a combination of both. Using the wrong method can create immense liability.
- Document Post-Repair Validation: After any collision repair, suspension work, or windshield replacement, insist on a printed report confirming successful calibration. This documentation is crucial proof that the safety systems were restored to OEM specification and can protect you from a denied claim.
- Assess Pre-Service: Before authorizing work like a wheel alignment, ask the shop if they have the capability to perform the necessary ADAS recalibration that may be required afterward. If they don’t, you may need to take the car to a dealership or specialist immediately after.
Key Takeaways
- The effectiveness of ADAS is highly variable and dependent on ideal weather and light conditions, limiting its real-world reliability.
- The long-term cost of ownership is significantly impacted by expensive, mandatory sensor calibrations required after common repairs.
- Driver over-reliance on these systems, or « automation complacency, » creates a new human-factor risk that can offset the technology’s benefits.
How to Prevent « Phantom Braking » Events on the Highway?
Perhaps one of the most unsettling failure modes of modern safety systems is « phantom braking. » This occurs when the Automatic Emergency Braking system falsely detects an obstacle and applies the brakes suddenly and without warning, creating a significant risk of a rear-end collision. From an actuarial perspective, a feature that can, by itself, *cause* an accident represents a complex new liability. While designed to prevent collisions, its malfunctions introduce a novel and dangerous event type that must be factored into the vehicle’s risk profile.
These are not isolated incidents. The NHTSA has received thousands of complaints from owners across multiple brands regarding unexpected braking events. The causes are often mundane, yet the consequences can be severe. Understanding the common triggers is the first step toward mitigation for both owners and insurers.
Case Study: Analysis of Nissan AEB Phantom Braking
An examination of complaints related to Nissan’s AEB system reveals several common root causes for phantom braking and false « Front radar unavailable » warnings. The most prevalent cause is simply dirt, ice, or other debris blocking the radar sensor, a fix that costs nothing but requires driver diligence. Other causes include misaligned radar after minor impacts (requiring costly recalibration), software glitches that necessitate updates, and weather-related interference. As one technical analysis confirms, « Rain, snow, fog, and other weather conditions can affect the sensors and cameras, leading to temporary system malfunctions. » Preventive measures identified from this data include weekly cleaning of sensor areas, researching model-specific phantom braking reports on the NHTSA database before purchase, and being aware of the system’s limitations in adverse weather.
For the vehicle owner, prevention is a matter of proactive maintenance and situational awareness. Regularly cleaning the areas on your grille and windshield that house camera and radar sensors is the single most effective preventive measure. Furthermore, understanding that the system is more prone to error in heavy rain, snow, or when driving towards a low sun can help you remain more vigilant and prepared to override a potential false activation. Ultimately, preventing these events comes down to treating the system as an assistant, not an autonomous pilot.
The final actuarial verdict is that advanced safety systems introduce as many new risk variables as they mitigate. Therefore, to truly evaluate the ROI of a safety package, a buyer must move beyond the hope of a simple discount and instead conduct a personal risk assessment, weighing the system’s known limitations and liabilities against their specific driving conditions and financial tolerance for high-cost repairs.